In some industries, revenue is called gross sales because the gross figure is calculated before any deductions. In the long run, such initiatives may lead to better returns for company shareholders, rather than those gained from dividend payouts. Paying off high-interest debt also may be preferred by both management and shareholders, instead of dividend payments. Management and shareholders may want the company to retain earnings for several different reasons. Being better informed about the market and the company’s business, the management may have a high-growth project in view, which they may perceive as a candidate for generating substantial returns in the future.
- Understanding these entries is tricky for everyone at the start, but once you understand financial statement dynamics, it’s easier.
- In step 1, we need to show the huge cash outflow from the company used to fund the big asset.
- The reasoning behind this rule is that revenues increase retained earnings, and increases in retained earnings are recorded on the right side.
- Although retained earnings are not themselves an asset, they can be used to purchase assets such as inventory, equipment, or other investments.
- In essence, Retained Earnings represents the accumulated profits that a company has kept over time.
- Let’s look at depreciation in the first year of purchasing our big machine.
Understanding Retained Earnings
Either the company builds up its cash reserves from cash generated with sales, or it needs to get external funding. Our balance sheet is in balance, and net profit is equal to retained earnings. An alternative to the statement of retained earnings is the statement of stockholders’ equity. For example, company A which is a trading company has a net income of $25,000 which all of its respective income and expenses have already been transferred to the income summary account at the end of 2020. Revenue is the total amount of income generated by the sale of goods or services related to the company’s primary operations. Revenue is the income a company generates before any expenses are taken out.
Retained Earnings: Understanding Retained Earnings via T Accounts
- To gain a comprehensive understanding of retained earnings, one must delve into the world of T accounts.
- Thus, it is a liability of the company and it is credited as per the golden rules of accounting for personal accounts.
- However, it is important to be aware of the limitations and considerations when using T accounts for retained earnings, as they can impact the accuracy and usefulness of the information provided.
- On the other hand, mature companies with stable cash flows might opt to distribute dividends to reward shareholders or repurchase shares to enhance shareholder value.
- The decision depends on the company’s financial goals, growth prospects, and the preferences of its management and shareholders.
Retained earnings are the portion of a company’s net income that management retains for internal operations instead of paying it to shareholders in the form of dividends. In short, retained earnings are the cumulative total of earnings that have yet to be paid to shareholders. These funds are also held in reserve to reinvest back into the company through purchases of fixed assets or to pay down debt. Retained earnings serve as a crucial component of a company’s financial strategy, providing businesses with a solid financial base, flexibility, and the means to fuel growth. By retaining a portion of their profits, businesses can reinvest in their operations, pursue expansion opportunities, and maintain control over their resources.
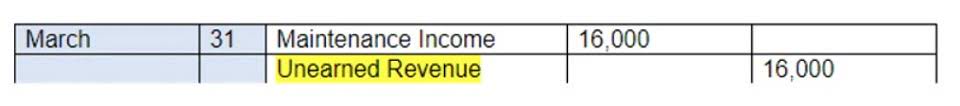
1: Retained Earnings- Entries and Statements
We need to move the value of the expense from accounts payable into cash when we make the payment. Notice that in the sales cycle we did not touch the expense Bookkeeping for Consultants account, even though we debited the Cost of Sales. This is because Cost of Sales is inherently linked to sales and therefore varies with business performance, while expenses are non-variable — they do not fluctuate with business performance.
Unit 3: The Accounting Cycle
Over the same duration, its stock price rose by $84 ($227 – $143) per share. One way to assess how successful a company is in using retained earnings is to look at a key factor called retained earnings to market value. It is calculated over a period (usually a couple of years) and assesses the change in stock price against the net earnings retained by the company.
Retained earnings, as the name suggests, refer to the portion of a company’s profits that it chooses to retain rather than distribute to shareholders as dividends. These earnings play a vital role in the financial health and long-term sustainability of a business. From the perspective of business owners, retained earnings represent a valuable source of capital that can be reinvested to fuel growth and expansion. On the other hand, investors often view retained earnings as a measure of a company’s ability to generate profits and allocate them effectively.
This account is part of the Share Capital section of a company’s balance sheet and the retained earnings account is increased with an entry on the side of the account. can be used for reinvestment in the business or to pay down debt. Each of the accounts in a trial balance extracted from the bookkeeping ledgers will either show a debit or a credit balance. The normal balance of any account is the balance (debit or credit) which you would expect the account have, and is governed by the accounting equation. If the company had not retained this money and instead taken an interest-bearing loan, the value generated would have been less due to the outgoing interest payment.
- If a company’s retained earnings are less than zero, it is referred to as an accumulated deficit.
- It involves paying out a nominal amount of dividends and retaining a good portion of the earnings, which offers a win-win.
- Retained earnings are a type of equity and are therefore reported in the shareholders’ equity section of the balance sheet.
- T accounts are a visual representation of a company’s general ledger accounts, providing a snapshot of the debits and credits affecting a specific account.
- The main difference between retained earnings and profits is that retained earnings subtract dividend payments from a company’s profit, whereas profits do not.
- Ultimately, the best option depends on the company’s specific objectives and the prevailing market conditions.
- Retained earnings can typically be found on a company’s balance sheet in the shareholders’ equity section.
What Does It Mean for a Company to Have High Retained Earnings?
Though retained earnings are not an asset, they can be used to purchase assets in order to help a company grow its business. As a QuickBooks result, additional paid-in capital is the amount of equity available to fund growth. And since expansion typically leads to higher profits and higher net income in the long-term, additional paid-in capital can have a positive impact on retained earnings, albeit an indirect impact. By reinvesting profits back into the company, businesses can expand their operations, enter new markets, upgrade infrastructure, or acquire complementary businesses. This reinvestment can lead to increased revenue generation, economies of scale, and enhanced market share. For instance, a technology company may choose to allocate retained earnings towards hiring top talent, developing new features, or expanding its customer base, ultimately driving growth and profitability.
About The Author